Your 401(k) Is Loaded With Taxes.
Let's Find Out How Bad - Before The IRS Does.
The tax freight train is coming.
Most 401(k) owners never see it.
Take our free 30-second survey to see if you qualify for a one-on-one 401(k) Rescue Strategy session.
Scroll down for two free bonuses, our book on paying less tax, and a calculator that shows your RMD and Medicare surcharge.
Free 30-second survey. No obligation.
Takes less than a minute • 100% Confidential
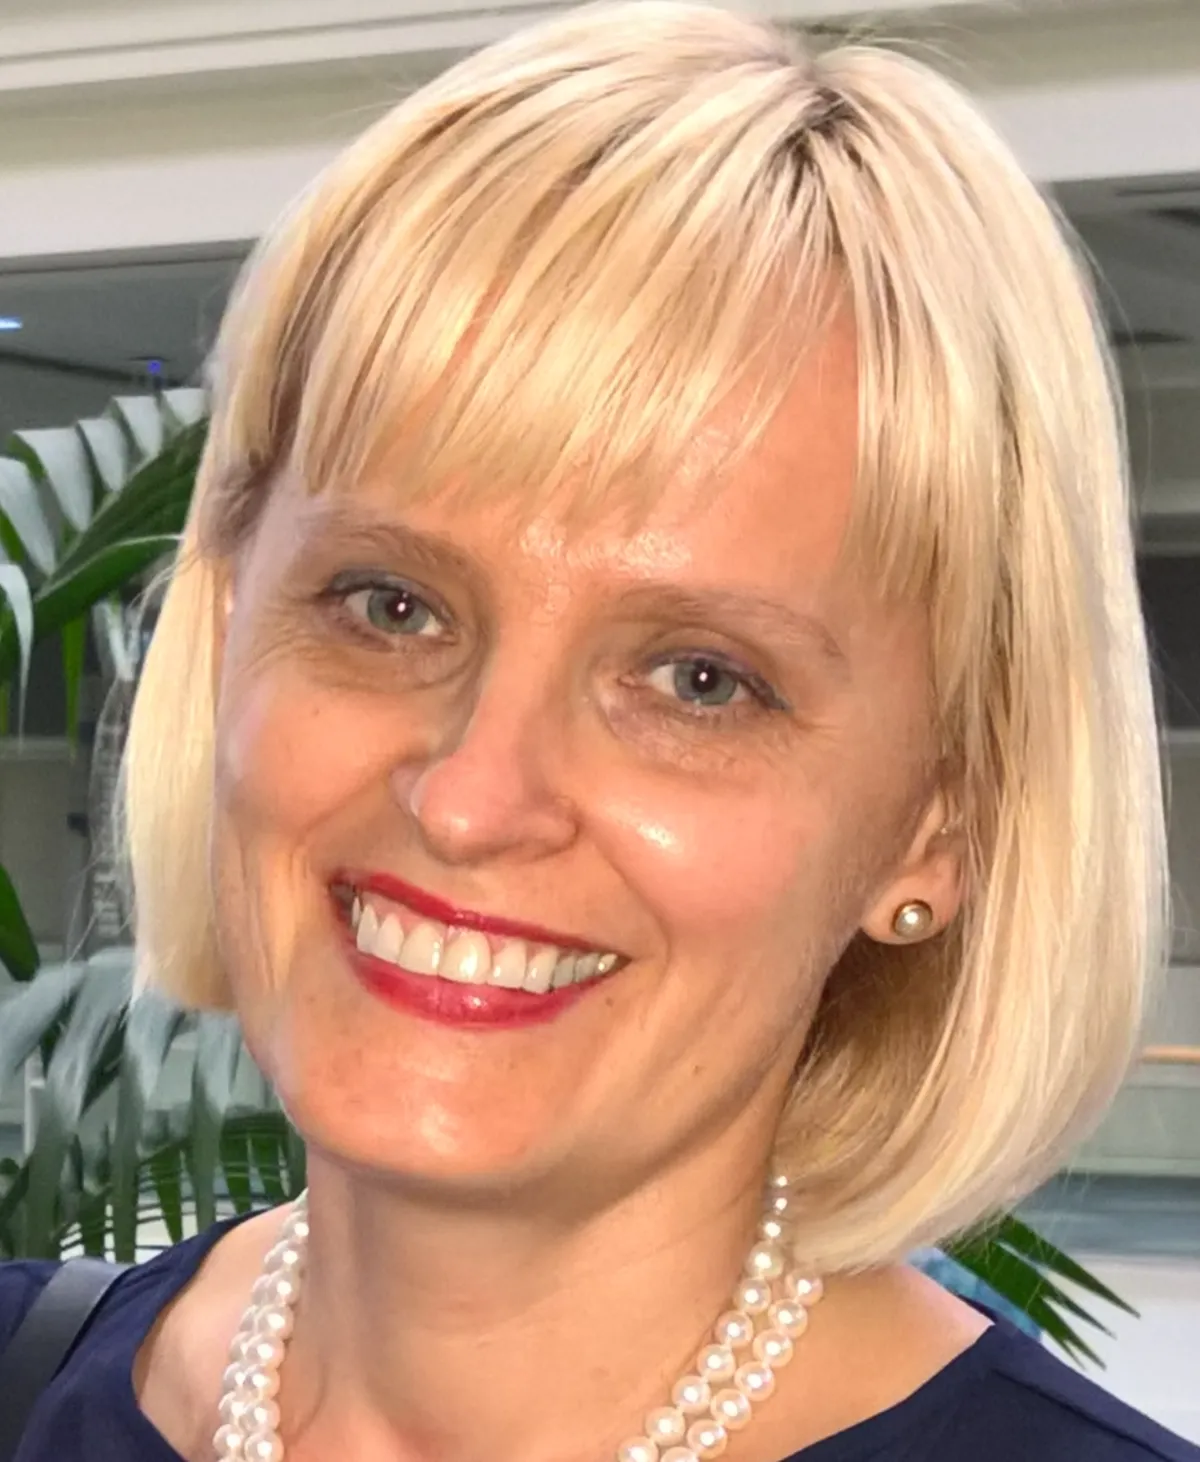
Olga Mitra
“My husband Sunny and I have been doing this together for 25 years. In one conversation, we can show you an estimate of how much tax the IRS may take - and three moves that may reduce it.”
How will this change your Tax Liabilities?
- See your own number: what the IRS may take from your 401(k) or IRA, and when.
- Understand which of the 9 tax traps may apply to you, in plain English.
- Learn the three rescue moves that can turn a forced tax bill into a plan.
- Leave with a clear next step, whether or not we end up working together.
THE PROBLEM NO ONE WARNED YOU ABOUT
At Age 73, the IRS Forces You to Withdraw - Whether You Need the Money or Not.
It’s called an RMD - Required Minimum Distribution. The government decides how much you must pull out of your 401(k) or IRA every year, and you pay income tax on every dollar. No exceptions. No negotiation.
For savers with $250,000 or more, those forced withdrawals can push you into a higher tax bracket, trigger IRMAA Medicare surcharges, and tax up to 85% of your Social Security. Three bills you didn’t know were coming - all at once.
For a large 401(k), forced withdrawals can add up to hundreds of thousands of dollars in taxes over a retirement - and the number grows as the account compounds. The call shows you your own estimate.
The good news: there are legal tax strategies that may reduce that burden by 50% or more. But you have to act before the withdrawals begin.
Find your number first. Everything else follows.
Two Kinds of Retirement Stories
Which one are you on track to write?
❌ Winging It
→ Never modeled their RMD tax bill
→ Hit with IRMAA surcharges at 73
→ Up to 85% of Social Security taxed
→ Roth conversion window closed
→ Leaves a massive tax bill to heirs
✅ With a Rescue Plan
→ Knows their exact tax exposure number
→ Converts strategically before 73
→ Keeps Social Security largely tax-free
→ Stays under IRMAA thresholds
→ Passes wealth to heirs tax-efficiently
No Cost · No Obligation30 Minutes · Phone or Zoom
What happens after you take the survey
1
Find out if you qualify
After you take the survey, we’ll tell you if you qualify for our free one-on-one meeting and two free bonuses.
2
Pick a time that suits you
Choose a time on our calendar. We will send you a reminder.
3
Meet with us, no pressure
We look at your numbers together, show you which traps may apply, and explain your options. You decide what to do next.
After Your Session, You’ll Receive Two Free Bonuses
Yours whether you do business with us or not. No obligation. It’s our way of thanking you for your precious time.
🎁 Two free bonuses for everyone who takes the call
BONUS #1 · THE BOOK
How to Beat the IRS, Legally
By Sunny Mitra & Edward A. Lyon, JD - co-authored with a tax attorney who appeared on CNN, Fox News, MSNBC and CNBC over 300 times
A $19.99 value - yours free after your call · Digital download
What the book is about: a plain-English guide to the legal ways everyday taxpayers and retirees can keep more of what they earn and save. Written with a tax attorney who spent decades teaching other tax professionals, it shows how the wealthy minimize taxes while plain-ahead and quietly outmaneuver everyone else.
- Why the tax code is built to reward those who know the rules
- Legal, IRS-recognized ways to reduce what you owe - no loopholes, no tricks
- Why a good strategy beats a good guess, and what to ask your CPA
BONUS #2 · THE CALCULATOR
The Empire Engine Calculator
Find your personal number first - live, personal, and built for your 401(k) and IRA balances
Yours free after your call
Not like the calculators you've seen online. Most retirement calculators stop at one number: your Required Minimum Distribution. The Empire Engine goes further. Enter your balances, age, and income, and it shows how federal tax brackets, Medicare Part B and D surcharges, a market drop and Social Security taxation stack on top of each other - year by year.
- Your projected RMD tax exposure from age 73 forward
- Your IRMAA Medicare surcharge risk
- What a 20% market drop does to your account - and why your tax bill barely moves
- A side-by-side look at what the Three Rescue Moves could change
Another thank-you for your time - yours to keep, whether you do business with us or not. Estimates are for education only, not tax advice.
The 9 Tax Traps That Torment Retirees!
If you've been saving in a 401(k) or IRA for more than 10 years, you may be facing at least 4 of these 9.
1The Roth Conversion Secret
Everyone says a Roth conversion means a bigger tax bill. Almost no one tells you that, with the right strategy, you may be able to convert and still cut your taxes by 50% or more when you file your return the next year. That's the part we walk you through.
2The RMD Ambush
Forced withdrawals at 73 that can push you into a higher bracket than you ever paid while working.
3The IRMAA Surcharge
Medicare Part B and D premiums that spike when your income crosses certain thresholds - often triggered by a single RMD.
4The Social Security Tax Trap
Up to 85% of your Social Security benefits become taxable once your combined income exceeds a certain level.
5The Widow's Penalty
When a spouse passes, the survivor files single - and often faces a much higher tax rate on the same income.
6The Heir's Tax Burden
Under current law, most non-spouse heirs must empty inherited IRAs within 10 years - and pay taxes on every distribution.
7The Conversion Window Trap
There's an optimal window to convert before 73. Every year you wait without a plan is a year of that window closing permanently.
8The W-2 “no options” myth
Too many people think that a W-2 paycheck means your hands are tied. There may be more options than you think.
9The one-roof advisor gap
A tax strategist, a CPA, a financial advisor and a tax attorney who actually work together are rare. Learn what to look for, and why it matters.
Free 30-second survey. No obligation.
Takes less than a minute • 100% Confidential
THE THREE RESCUE MOVES - YOUR BLUEPRINT FOR A SMALLER TAX BILL
Every trap has an answer. On the call, we show you the three moves that - together - form a complete rescue plan. Then we show you which ones apply to your specific situation.
1
Strategic Roth Conversion
Moving money from taxable to tax-free at the right time - often in the years between retirement and age 73 - may reduce or even eliminate years of forced tax bills. We show you the right amount and timeline for your account size.
2
Annual Tax Savings Strategy
Objective: To explore ways to reduce your yearly tax bill, whether you’re a W-2 employee or a 1099 entrepreneur.
3
Tax Recovery Strategy
Objective: To show how you may be able to recover taxes you overpaid in the last 3 years, before that window closes.
None of these moves require you to change advisors, close accounts, or make any decision on the call. The only goal is to show you your number - and what’s possible.
WHAT TO EXPECT
Here’s Exactly What Happens on the Call
No PowerPoint. No pitch deck. Just a direct conversation built around your numbers.
We Run Your RMD Projection
Using your account balance and age, we calculate your Required Minimum Distributions from age 73 forward - including the tax bracket impact year by year.
We Identify Your Traps
We walk through the 9 traps and flag which ones are already in your path - IRMAA exposure, Social Security taxation, widow’s risk, heir burden.
We Show You the Rescue Moves That Apply
Not every move fits every person. We show you which of the Three Rescue Moves makes sense for your timeline, balance, and income - and what it could save you.
You Decide What Comes Next
We never close on a call. If what you see makes sense, we schedule a follow-up. If not, you leave with clarity and a number you didn’t have before. Either way, you win.
Meet Olga & Sunny
We are a husband-and-wife team, and Olga is the CEO of Atlanta First Guarantee. Together we have spent 26 years helping retirees and pre-retirees keep more of what they worked for.
Sunny has decades of experience in banking, insurance and tax-mitigation planning, and is the author of four published books on the subject.
The CPA firm we partner with helps clients recover over $2 billion in overpaid taxes every year. Behind us is a full team, with tax strategists, a CPA, a tax attorney, a financial advisor, and an insurance specialist, operating as a fractional family office with one principle at the center: tax is an expense. And expenses can be managed.
We can’t meet with everyone - but if you qualify, we’d love to meet with you.
WHY NOW
Every Year You Wait, the Window Gets Smaller
- Once forced withdrawals begin at 73, your options shrink. The years before are your planning window.
- Tax rates change with the law. Planning at today’s rates may help you avoid paying more later.
- One big income spike can trigger higher Medicare premiums (IRMAA).
- Your account compounds every year, and so does the tax bill that comes with it.
- The survey is free. There’s no cost to knowing your number.
“The best time to run your 401(k) tax projection was 10 years ago. The second best time is today.”
What our clients say
“
I was speaking with Sunny on the phone regarding my retirement. He listened, took notes, and came up with a solution. … It has been almost three months since my first phone call with Sunny, and I am in control of my tax situation. I see a clear path before me paved in financial freedom. … I hope one person reads this and reaches out to Sunny. If that person is you, I promise you will not be disappointed.”
Lisa Menconi
California
“
Such a great job and I am very, very thankful and it worked out so well for us, so thank you for all your hard work. Olga, you kept your word and delivered more than you promised. We are very pleased, and we’ll definitely refer others to you.”
Sharon Patterson
Georgia
“
Sunny Mitra is an insurance agent who is not only knowledgeable but also very professional. He is very reliable and always makes himself available when you need him despite his busy schedule. Helping his clients is his success, which separates him from other insurance agents who focus mostly on their gains.”
Celestin Kagorora
Florida
Individual experiences vary.
Step 1 of 2: See If You Qualify
Please take the 30-second survey. It helps us prepare for your session.
Our Promise to You
This is a no-obligation strategy call. We will never pressure you to buy anything, sign anything, or make a decision on the spot. You will receive honest, direct analysis of your tax exposure - and you can do whatever you want with it afterward.
No Cost. No Pitch. No Pressure.
COMMON QUESTIONS
FAQ
Who is this for?
Retirees and pre-retirees with $250,000 or more in a 401(k), Traditional IRA, or other tax-deferred account, including business owners. Ideal if you’re between ages 55 and 75 and haven’t done a formal projection on your retirement savings.
Is this really free? What’s the catch?
It’s genuinely free. We offer this session because it’s the most direct way to show what the 401(k) Rescue Strategy can do for you. If what you hear makes sense, some clients ask us to help implement a plan - but that conversation only happens if you bring it up.
Will I be pressured to buy something?
No. We will show you your numbers and explain your options. You decide what, if anything, makes sense for you.
Do I need to bring anything to the session?
Just a rough idea of your current account balances, your age, and whether you’re currently taking withdrawals. We don’t need statements or tax returns for the initial session - we work from estimates and run the projections live.
I already have a CPA or financial advisor. Should I still meet with you?
Yes - especially if your advisor has never shown you a forward-looking tax projection on your retirement accounts. We don’t replace your CPA or advisor. We help you ask better questions and bring your own numbers to the conversation. Many advisors focus on growth rather than tax efficiency, so this session may fill a gap that surprises even experienced investors.
What exactly are the Three Rescue Moves?
They are the Strategic Roth Conversion, the Annual Tax Savings Strategy, and the Tax Recovery Strategy - three legal tax strategies that, together, may form a complete framework for reducing the tax impact of large tax-deferred retirement accounts.
What if I can’t make my appointment?
Life happens. Just use the link in your reminder to pick a new time - no penalty, no problem.
START HERE
START WITH THE SURVEY
🎁 Two free bonuses after your call: the digital book How to Beat the IRS, Legally (a $19.99 value) and the Empire Engine Calculator - yours whether or not we work together.
Take the Survey
If you qualify, choose a time on our calendar. Olga or Sunny will call you then. Have a rough idea of your account balances handy - that’s all you need. Our average appointment time is 30 to 45 minutes unless you have more questions.
Walk away knowing your projected tax exposure - and what the Three Rescue Moves could save you. No obligation, no pressure. Our job is to show you. Your job is to decide.
Atlanta First Guarantee
wealthcreator.life | Athens, Georgia | Atlanta First Guarantee
© 2026 Atlanta First Guarantee. All rights reserved. | Privacy Policy | Disclaimer